Short answer
Sometimes. It depends on how your policy words the causes of loss it covers, whether the damage counts as direct physical loss, and which exclusions apply. Many owners get part of the cost covered for the damaged building and belongings, but gaps remain. Read your declarations page, the summary page of your policy. Call your insurer early, and ask your state victim compensation program about cleanup costs.
Will my homeowners policy actually pay for cleanup after a crime in my house?
The honest answer is that it depends on your own policy, not on the fact that a crime happened. Insurers do not have a single category called crime scene cleanup. They ask two things. Did a covered event cause direct physical damage to your home or belongings? And are cleaning and repair reasonable ways to fix that damage?
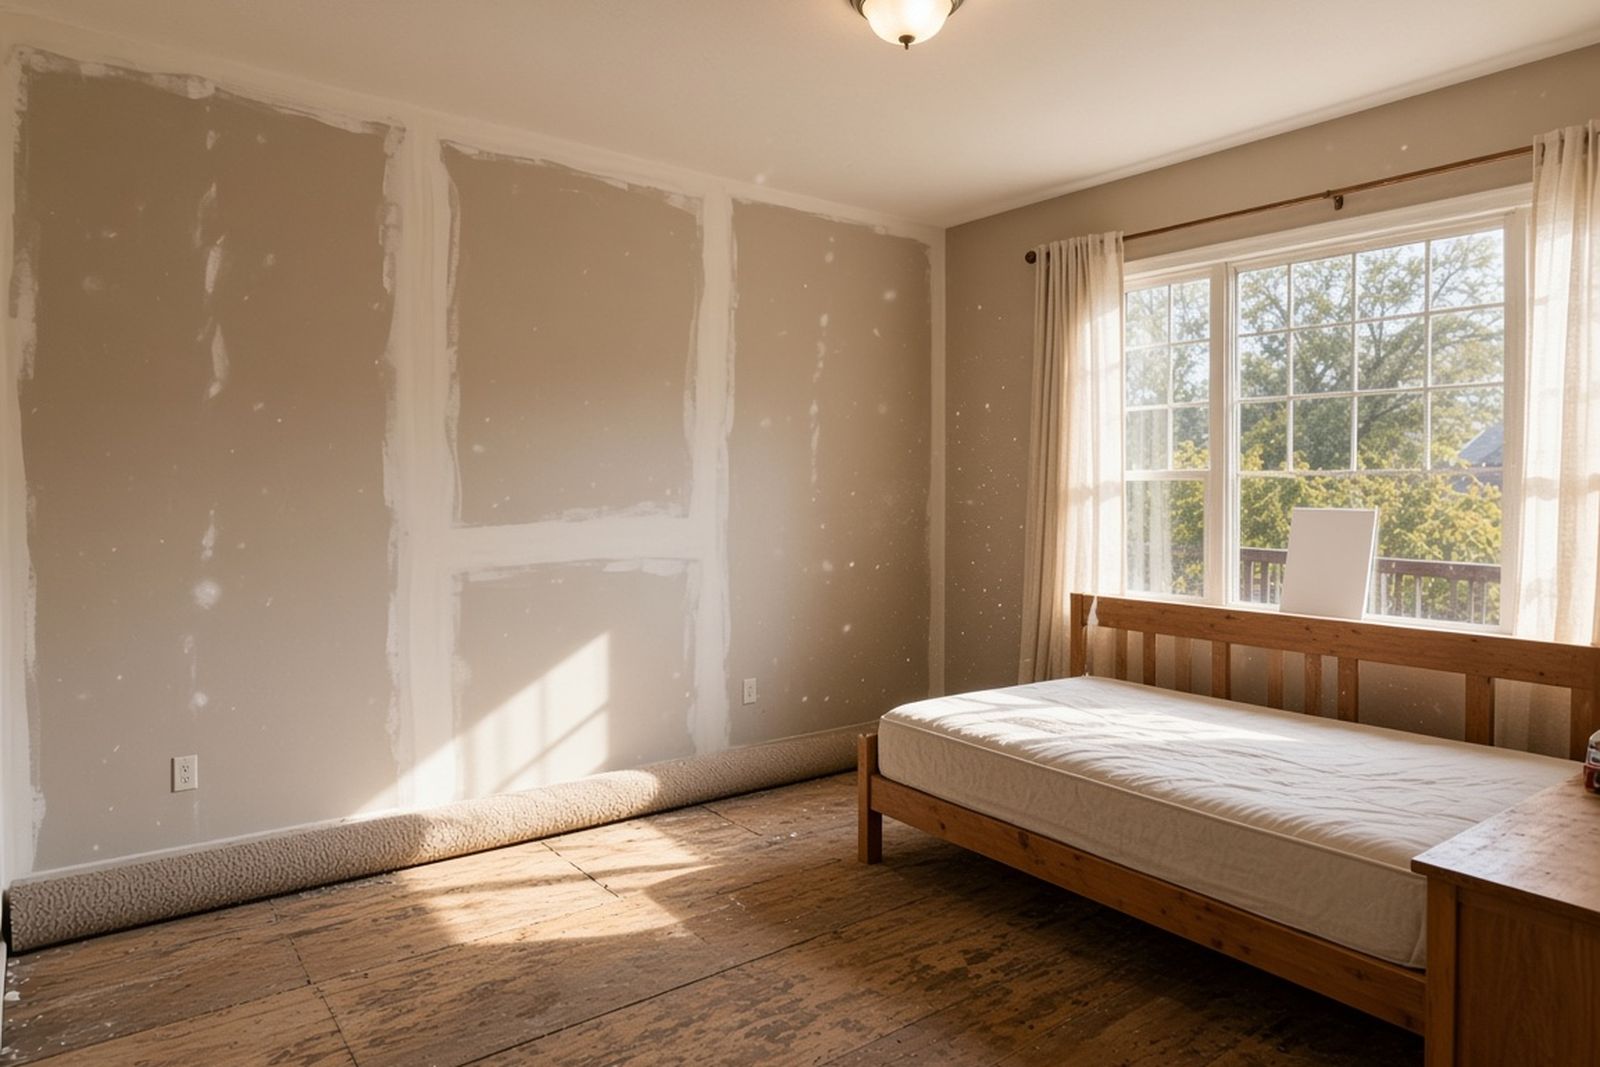
After a break-in, an assault or a violent incident in your home, the physical damage can take many forms. There may be blood on carpet and drywall, broken doors and windows, and fingerprint powder on surfaces. Some belongings may no longer be safe to keep. Some of these fit neatly into standard coverage. Others fall into gray areas that you will need to talk through with your adjuster.
Policy wording varies by insurer and by form. So read your own policy and ask your insurer before you assume anything is covered or excluded.
The parts of a scene most likely to be covered
Think of the scene in layers. The building is one layer: flooring, subfloor, drywall, trim, doors and windows. Your personal property is a second layer: furniture, rugs, clothing and electronics. The cost of living somewhere else, if you cannot stay in the home, is a third layer. Some policies handle that under a separate part of the coverage.
Many homeowners forms list damage from vandalism or malicious mischief as a covered peril, meaning a cause of loss the policy pays for. Forced entry during a burglary is commonly handled under the theft or vandalism sections. Cleanup of blood and body fluids may be treated as part of repairing that damage. Your adjuster decides how the pieces fit together under your wording.
- Building materials that soaked up blood or other fluids and must be removed and replaced
- Doors, locks and windows damaged by forced entry
- Belongings that cannot be safely cleaned and must be thrown away
- Added living expenses if you cannot live in the home during cleanup, where your policy includes that coverage
- Residue from police work, such as fingerprint powder, which some insurers treat as part of the loss
Where claims run into trouble
Gaps tend to show up at the edges. An exclusion for intentional acts may apply if the person who caused the damage is also an insured member of your household. Your deductible can swallow much of a smaller claim. Some policies cap what they pay for certain kinds of property. Some treat odor or cleaning differently from physical replacement.
Timing matters too. Most policies require you to report a loss promptly and to take reasonable steps to prevent more damage. If you wait weeks to report, or let soiled materials sit and spread, an adjuster may raise questions you could have avoided.
Owners, renters and managers
Who owns or rents the property matters, because different policies pay for different parts of the loss. If you own a single-family home, your homeowners policy usually covers both the building and your belongings. If you own a condo, the building's master policy may cover common areas and some parts of the structure. Your unit policy covers interior finishes and belongings. The association's documents decide where one ends and the other begins.
If you rent, your landlord's policy generally covers the building. Your renters policy, if you have one, covers your personal property and possibly temporary housing. Tenants are sometimes surprised to learn that a landlord's coverage does not replace their ruined couch or clothing.
If you manage a rental where a crime took place, tell the owner and the owner's insurer promptly. Keep the tenant informed about who is arranging the cleanup. Clear communication early keeps two parties from each assuming the other has called a cleanup company.
What the insurer needs from you
Adjusters work from records. The more clearly you can show what happened, what was damaged and why the proposed work is needed, the easier the conversation becomes. You do not need to become an expert. You just need to gather a few things in one place.
Ask the police for the report number and the date the scene was released back to you. Photograph affected rooms from the doorway. Do not enter areas that still hold blood or body fluids. Keep receipts for anything you pay out of pocket, including lock changes and temporary lodging.
- Police report number and name of the investigating agency
- The date and time the scene was released
- Photos or video taken from a safe distance
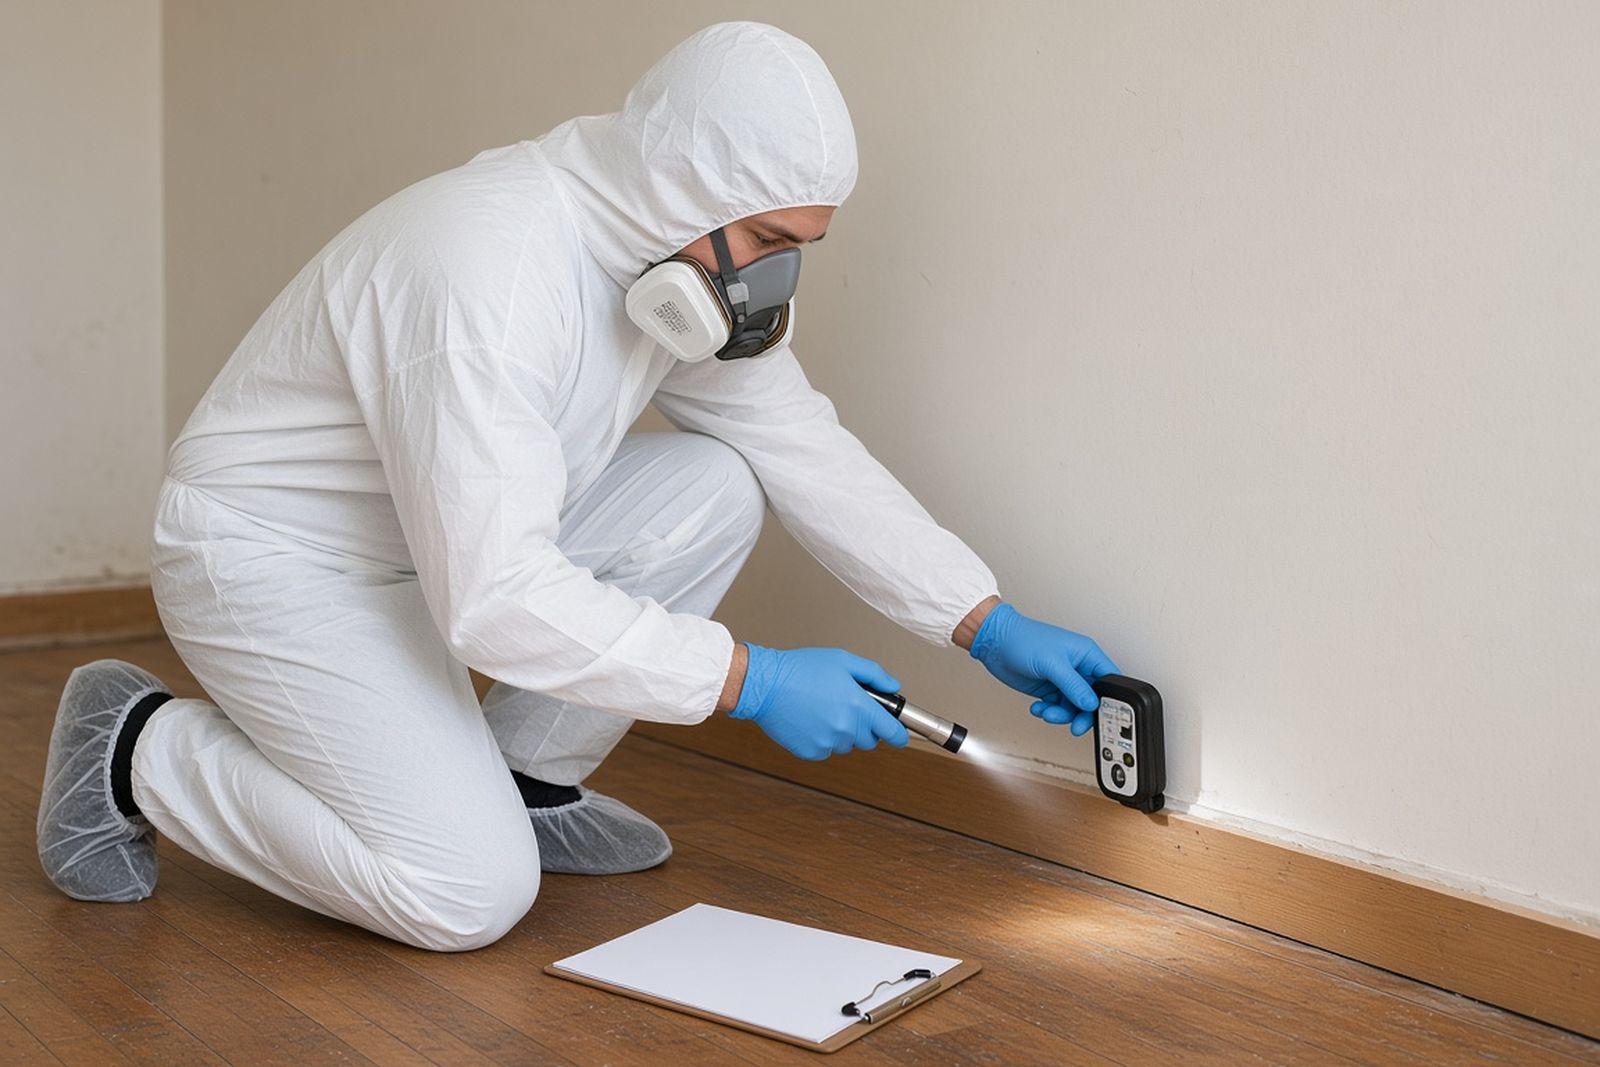
- A written work plan and estimate from the cleanup company, itemized by area and material
- Waste disposal records showing where regulated material was taken
- A list of discarded belongings with rough age and replacement value
What if my policy does not cover it, or covers only part?
If you are the victim of a crime, your state victim compensation program may pay back some cleanup costs that insurance does not pay. These programs typically require a police report and your cooperation with police. You must also file a claim within a set window. They are generally a payer of last resort. That means they look at what insurance covered first.
Limits differ widely. The California Victim Compensation Board announced in 2022 that it reimburses crime scene cleanup expenses up to $1,709 per claim, raised from $1,000 in July 2022. Other states set different caps, and the rules on who qualifies are not the same everywhere. Call your state program or a local victim advocate to learn what applies to you.
A victim advocate attached to the police department or prosecutor's office can help you file. They often know which documents the compensation program will ask for. They can also explain how an insurance payment affects whether you qualify.
One claim from break-in to payment
To see the process step by step, walk through an illustrative claim. A homeowner returns from a weekend away to find the back door forced open. An intruder cut himself breaking a glass panel. He left a trail of blood through the kitchen and across a carpeted hallway before fleeing with electronics.
Police process the scene, dust for prints and release the home the next afternoon. The homeowner calls the insurer that evening and gives the police report number. She asks whether a cleanup company can begin. The adjuster asks for photos, an itemized estimate and a list of stolen and damaged items.
The cleanup company's work plan treats two areas differently. The kitchen tile can be cleaned and disinfected. The hallway carpet and pad soaked up blood and must be removed. The door and glass are listed as repair items. The insurer applies the theft and vandalism sections, subtracts the deductible and asks follow-up questions about the carpet. The homeowner then contacts the state victim compensation program about the amount left over.
Every step in this scenario is an illustration. Your insurer, your policy form and your state program will shape how your own claim is decided.
Should the cleanup company bill my insurance directly?
It can help, as long as you read what you sign. Many cleanup companies offer to work with your insurer, and that can cut the paperwork you handle while you are under stress. Before you sign, read the authorization with care. Some agreements assign your claim benefits to the contractor. Some make you responsible for any amount the insurer declines to pay.
Ask the company to explain, in plain terms, what happens if the adjuster approves less than the estimate. Ask whether they will provide the itemized work plan, photos and disposal records the insurer needs. A reputable company will answer these questions without pressure. It will not promise that a claim will be approved.
- Who pays the balance if the claim is partly denied?
- Does the agreement assign your benefits, and can you take that back?
- Will you get copies of everything sent to the insurer?
- Does the company wait for the adjuster's approval before starting non-emergency work?
What to do today while you wait for answers
Report the loss to your insurer as soon as you reasonably can. Write down the claim number and the name of anyone you speak with. Keep people and pets out of affected rooms. Do not try to scrub blood from soft or absorbent materials yourself. That can spread the mess and may make the insurer's review harder.
Ask your cleanup company for a written work plan before major work begins, unless an urgent safety issue means the area must be closed off right away. Keep every receipt. If the claim is denied or underpaid, ask for the denial in writing with the specific policy wording cited. Then contact your state victim compensation program and your state insurance department for guidance.
Crimes in the home leave more than physical damage. It is normal to feel unsettled in your own space for a while. A victim advocate can connect you with counseling as well as financial help. Asking for that support is part of recovering. It is not a sign that you are not coping.